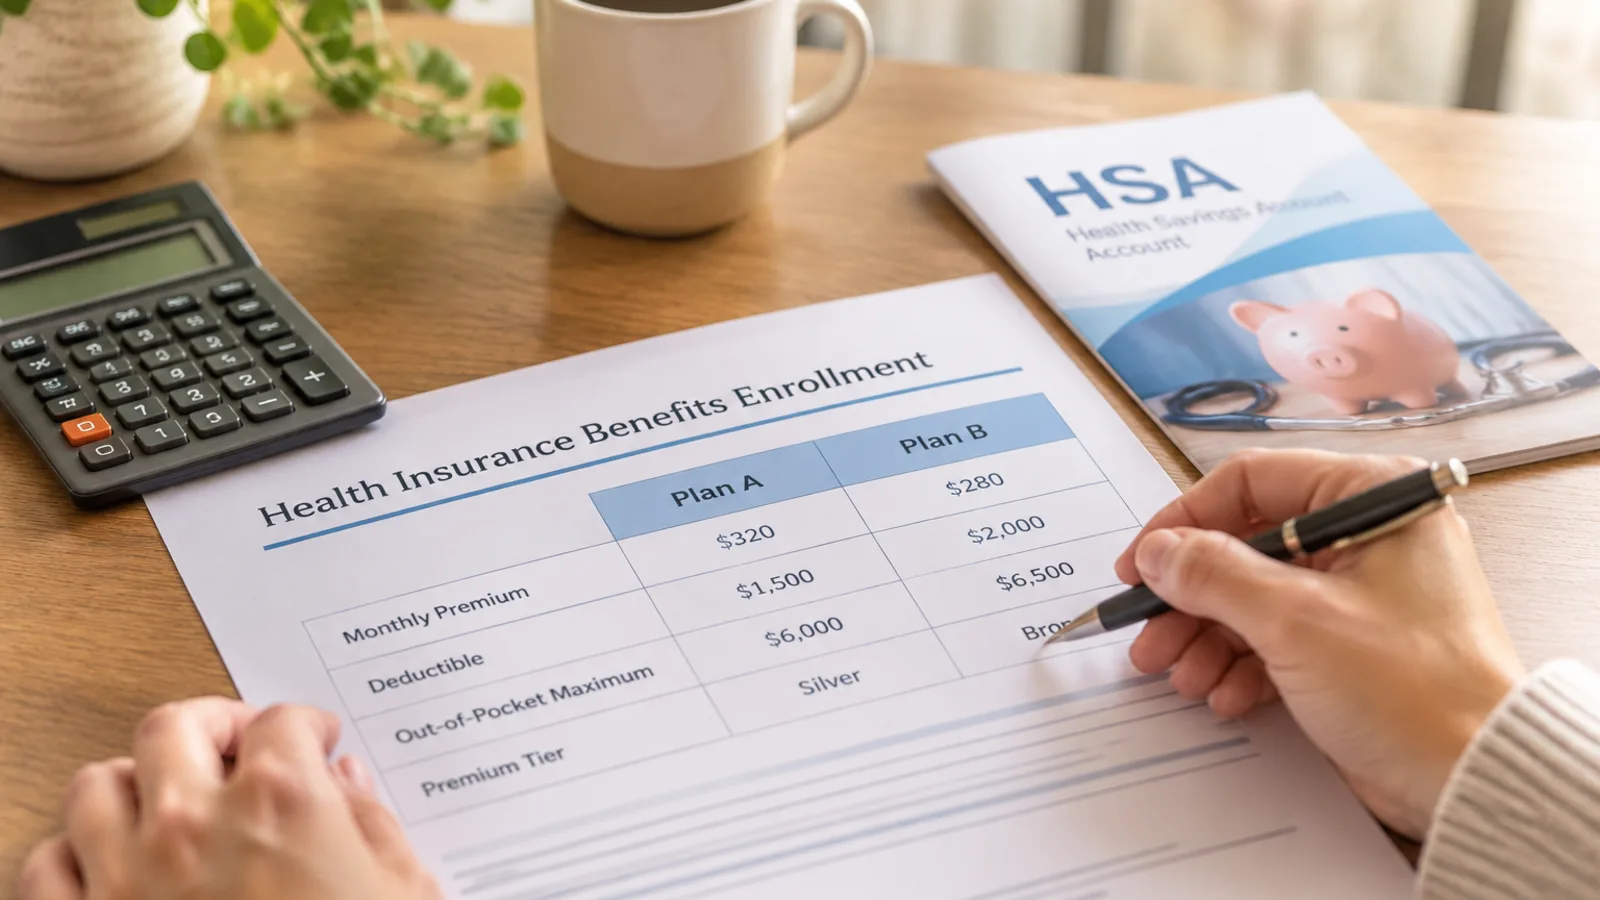
Your benefits administrator says the HSA-eligible plan will "save you money on taxes." Your colleague swears by hers. But when you see that $3,500 deductible—more than double your current plan—the tax break suddenly feels abstract. Here's the truth: is an HSA worth it depends on three concrete factors: how much you'll actually save in taxes, how much risk you can afford if someone gets sick, and whether your monthly budget can handle both lower premiums and higher out-of-pocket costs. This guide walks you through the math and the trade-offs so you can decide if an HSA makes sense for your situation.
What You're Actually Trading: Lower Premiums for a Higher Deductible
HSA-eligible plans work on a simple trade: you pay less each month in premiums, but you're on the hook for more expenses before insurance kicks in.
The premium savings (what you keep each month)
Most HSA-eligible plans cost $150 to $300 less per month than comparable PPO or HMO plans. That's $1,800 to $3,600 back in your pocket annually—real money that shows up in every paycheck.
The deductible risk (what you'd owe if you need care)
The catch is the deductible. HSA-eligible plans currently require minimum deductibles of at least $1,650 for individuals or $3,300 for families, though these thresholds adjust annually. Many plans run higher—$3,000, $5,000, even $7,000 for family coverage.
What does that mean in practice? If you need an urgent care visit for strep throat, you're paying the full $180. Break your wrist and need an ER visit? You're covering the $2,400 bill until you hit that deductible. Have a baby? That's often $8,000 to $10,000 in total costs, and you're responsible for everything up to your deductible and then your coinsurance after that.
Why this trade-off doesn't work the same for everyone
If you're healthy and rarely see a doctor, those premium savings compound year after year while you pay very little out-of-pocket. But if you have ongoing medical needs—regular physical therapy, expensive prescriptions, specialist visits—you'll hit that deductible fast, and the premium savings may not cover the difference.
The Triple Tax Advantage—and What It's Actually Worth in Dollars
How the three tax breaks work
HSAs offer three tax benefits. Contributions reduce your taxable income (you don't pay federal or state income tax on money you put in). The account grows tax-free (any interest or investment gains aren't taxed). And withdrawals for qualified medical expenses are tax-free (you're never taxed on money you use for healthcare).
What you'd actually save based on your tax bracket
The tax savings depend on your income. Current contribution limits are $4,300 for individuals and $8,550 for families, though these amounts adjust each year. If you're in the 22% federal bracket and contribute $3,000 to your HSA, you save $660 in federal taxes plus whatever your state takes. Contribute the individual maximum of $4,300, and that's $946 in federal savings alone.
Higher earners benefit more. Someone in the 32% bracket saving the family maximum of $8,550 keeps $2,736 that would otherwise go to taxes.
The catch: you only win if you can afford to contribute
Here's where the theory meets reality. Those tax savings only materialize if you actually put money into the HSA. If your budget is tight and you're already struggling to cover that high deductible, you may not have cash left over to contribute. You can't save on taxes with money you don't have to set aside.
The Break-Even Question: When Does the HSA Come Out Ahead?
Low-cost year scenario (routine care only)
Let's say you're 29, healthy, and your only medical expenses are an annual physical (covered preventively) and one sick visit ($180). You save $200/month in premiums ($2,400/year) and contribute $2,400 to your HSA, saving $528 in taxes at the 22% bracket. Your total benefit is roughly $2,700. Even after paying that $180 out-of-pocket, you're nearly $2,500 ahead.
High-cost year scenario (surgery, chronic condition, pregnancy)
Now imagine you need regular physical therapy and hit your $3,200 deductible by June. You're still saving $180/month in premiums ($2,160/year), and if you manage to contribute $1,200 to your HSA, you save about $264 in taxes. Total benefit: $2,424. But you paid $3,200 out-of-pocket, compared to maybe $2,600 under your old PPO. You're out roughly $800 this year.
The multi-year view (why one bad year doesn't kill the strategy)
Here's the thing: most people don't have high medical costs every single year. If you use an HSA for five years and four of them are low-cost, the cumulative premium and tax savings often outweigh that one expensive year—especially if you're building a balance that rolls over and grows.
Four Situations Where an HSA Usually Makes Sense
You're young and healthy with an emergency fund. If you rarely need care and have three to six months of expenses saved, you can absorb an unexpected medical bill without derailing your finances. The premium and tax savings compound in your favor.
You're a high earner looking for extra tax-advantaged space. Once you've maxed out your 401(k) and IRA, an HSA offers another place to shelter income from taxes. For someone earning over $100,000, the tax benefits are substantial.
You're planning for future medical expenses in retirement. You can invest HSA funds once your balance hits a threshold (often $1,000 to $2,000), turning it into a long-term health savings vehicle. Many people use HSAs as a stealth retirement account.
Your employer contributes generously to your HSA. If your company seeds your account with $1,000 or more, that free money can cover a big chunk of your deductible before you spend a dollar. This changes the math significantly.
Four Situations Where You Should Think Twice
You have ongoing medical needs. Regular specialist visits, expensive prescriptions, or chronic conditions mean you'll likely hit your deductible every year. A lower-deductible plan might cost you less overall.
You don't have an emergency fund. If a surprise $3,000 medical bill would go on a credit card or force you to skip other bills, the HSA's high deductible is too risky. Financial stability comes before tax optimization.
You have a family with young kids. Pediatric care is unpredictable—ear infections, broken bones, urgent care visits pile up fast. Families often find the predictability of a lower-deductible plan worth the higher premiums.
You're on a tight budget. If the premium savings barely cover your expected medical costs and you have no cushion to contribute to the HSA, you're not capturing the tax benefit that makes the plan worthwhile.
How to Run Your Own Numbers
Step 1—Calculate your total cost under each plan
Take your annual premium (monthly premium × 12) and add your expected out-of-pocket costs. Use last year's medical spending as a baseline. Don't forget prescriptions, specialist copays, and any planned procedures.
Step 2—Add back your tax savings from HSA contributions
Estimate what you can realistically contribute to an HSA. Multiply that by your tax bracket to find your tax savings. If your employer offers payroll deduction for HSA contributions, you'll also avoid FICA taxes (Social Security and Medicare), which boosts your savings beyond just income tax. Add your total tax savings back to reduce your overall cost.
Step 3—Stress-test with a high-cost scenario
Run the numbers again assuming you hit your full deductible. How much would you pay under each plan? If the HSA plan is only marginally better in a good year and significantly worse in a bad year, think carefully about your risk tolerance.
What to Know Before You Enroll
You can't contribute if you have other coverage. If you're enrolled in a health FSA (flexible spending account), covered by your spouse's non-HSA plan, or on Medicare, you're not eligible to put money into an HSA.
The money is yours forever. Unlike an FSA, HSA funds don't expire at year-end. Even if you switch to a different health plan next year, you keep the account and can still use it tax-free for medical expenses. You just can't make new contributions while on a non-HSA-eligible plan.
You can invest HSA funds once your balance hits a threshold. Most HSA providers let you invest in mutual funds or ETFs once you've saved $1,000 to $2,000. This turns your HSA into a long-term wealth-building tool, especially if you can afford to pay current medical expenses out-of-pocket and let the account grow.
Missing the contribution deadline means losing that year's tax benefit. You can contribute for the previous tax year up until the April tax deadline, but once that passes, you can't go back and fund prior years. If you don't use the contribution room, it's gone.
Frequently Asked Questions
Can I use an HSA if my spouse has a regular health plan?
Yes, as long as you're not covered by their plan. But if their plan covers you (even as secondary insurance), you're not eligible to contribute to an HSA.
What happens to my HSA money if I switch to a non-HSA plan next year?
The money stays yours forever. You keep the account and can still use it tax-free for medical expenses. You just can't make new contributions while you're on a non-HSA-eligible plan.
Is it better to pay medical bills out-of-pocket and let my HSA grow?
If you can afford it, yes. Paying expenses from your regular budget and leaving HSA funds invested turns it into a powerful retirement account. You can reimburse yourself years later for expenses you paid out-of-pocket, as long as you keep receipts.
What if I can't afford to max out my HSA contributions?
Contribute what you can. Even $50 per month saves you taxes and builds a buffer. The "max out or don't bother" advice ignores that partial contributions still work—they're just less powerful than the full amount.
Do HSA funds expire at the end of the year like FSA money?
No. HSAs roll over completely. There's no "use it or lose it" rule, which makes them much less risky than FSAs.
Ultimately, deciding if an HSA is worth it comes down to your health and your financial reality. For many people, the answer is yes—but not everyone. If you're healthy, financially stable, and can take advantage of the tax benefits, an HSA often comes out ahead over time. But if you have predictable medical costs, a thin emergency fund, or a family with unpredictable needs, a traditional plan might give you more peace of mind. Run your own numbers, stress-test the scenarios, and choose the plan that matches both your health status and your budget.
Join the conversation
Sign in — Sign in to join the conversation.